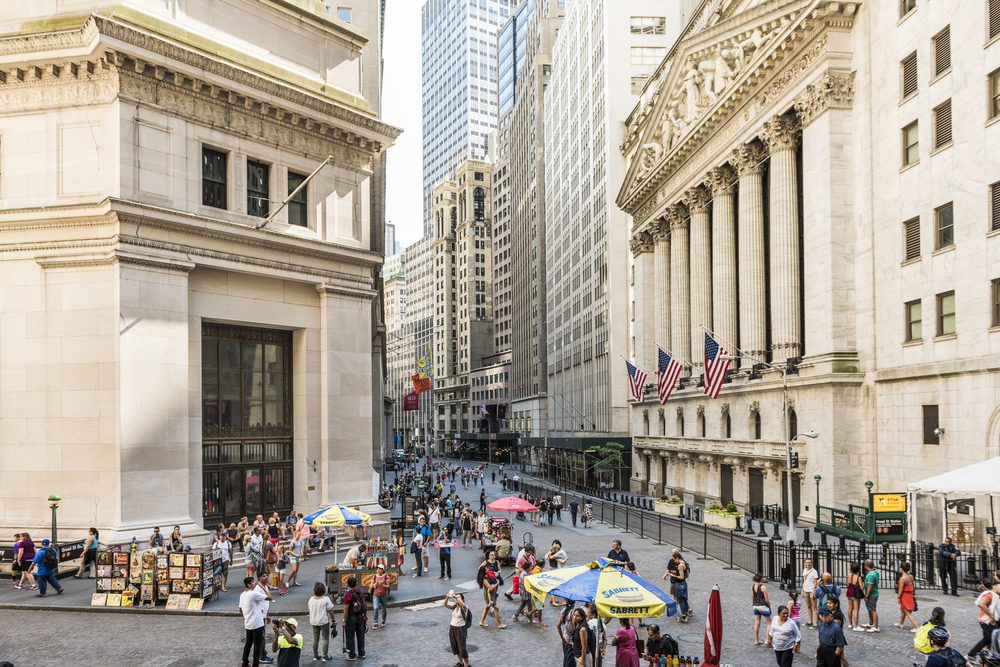
Americký akciový trh vstupuje do období, které je historicky považováno za méně příznivé – měsíce srpen až říjen bývají často poznamenány zvýšenou volatilitou.
Tentokrát je situace komplikována hned několika faktory. Patří mezi ně obnovené obchodní napětí, slabší data z trhu práce a nejistota ohledně budoucí politiky Federálního rezervního systému.
Prezident Donald Trump znovu oživil obavy z celních opatření, když pohrozil zvýšením sazeb vůči více než deseti zemím včetně Švýcarska. Tento krok přichází v době, kdy americká ekonomika vykazuje smíšené signály. Červencová zpráva o zaměstnanosti ukázala nárůst pouze o 73 000 míst, což je výrazně méně, než trh očekával. Navíc došlo k revizi směrem dolů u údajů za květen a červen. Míra nezaměstnanosti vzrostla z 4,1 % na 4,2 %, což přispělo k obavám z ochlazování trhu práce.
Na páteční data zareagovali i představitelé Fedu. Michelle Bowmanová i Christopher Waller zopakovali své obavy z vývoje zaměstnanosti a podpořili úvahy o možném snížení sazeb již v září. Trhy nyní podle všeho opět počítají s tímto krokem, přestože inflace v červenci vykázala největší měsíční nárůst od února.
I když některé makroekonomické ukazatele naznačují zpomalení, nelze zatím hovořit o recesi. Hrubý domácí produkt ve druhém čtvrtletí vzrostl, i když část tohoto růstu byla tažena předzásobením kvůli obavám z cel. Gary Pzegeo z CIBC uvedl, že současná fáze ekonomického cyklu se vyznačuje vyšší odolností – firmy mají možnost refinancovat a spotřebitelé stále těží z postpandemických stimulů.
Větší pozornost nyní míří mimo technologický sektor. Otázkou je, zda i další společnosti budou schopny pokračovat v investicích a kapitálových výdajích. Naopak technologické firmy stále potvrzují svou sílu. Microsoft (MSFT) i Meta Platforms (META) zveřejnily na konci července silné výsledky, což vedlo k výraznému růstu jejich akcií a pomohlo podpořit celý trh.
Pozitivní vliv velkých tech společností tak částečně tlumí negativní signály z jiných oblastí. Zatímco index S&P 500 klesl v pátek o 1,6 %, stále se drží 25 % nad dubnovým minimem. Nasdaq Composite je dokonce o 35 % výše od svého letošního dna.
Historie ukazuje, že srpen a září bývají pro americké akcie náročné. Podle údajů Dow Jones Market Data zaznamenaly indexy jako Dow Jones Industrial Average, Nasdaq nebo Russell 2000 v tomto období pravidelné poklesy. Například Nasdaq v srpnu v průměru vzrostl pouze o 0,3 %, přičemž září mívá ještě horší bilanci.
Říjen obvykle přináší mírné zlepšení, ale i zde jsou výkyvy časté. Investoři by proto měli zůstat opatrní. Nejbližší důležitou událostí je sympozium Fedu v Jackson Hole, které proběhne ve dnech 21.–23. srpna. Vystoupení předsedy Jeroma Powella může poskytnout další vodítka ohledně budoucí měnové politiky.
Na straně firemních výsledků budou pozornost poutat společnosti jako Walt Disney (DIS) a McDonald’s (MCD), které své výsledky zveřejní v následujícím týdnu. Investoři budou sledovat zejména vývoj spotřebitelské poptávky, která je jedním z klíčových ukazatelů kondice ekonomiky.
Navzdory výše zmíněným rizikům panuje mezi investory relativní optimismus. Trumpova celní politika je často používána jako vyjednávací nástroj, a nikoliv jako trvalá hrozba. Podobně Fed zatím nezahájil agresivní utahování a naopak může sáhnout k uvolnění, pokud si to ekonomika vyžádá.
Vývoj na dluhopisovém trhu zůstává složitější. Obavy z deficitu a vládního dluhu by mohly vést k tlaku na vyšší výnosy. Pokud však cla přinesou dodatečné příjmy a inflace zůstane pod kontrolou, nemusí být dopad dramatický.
Jak připomněl Eric Diton ze společnosti The Wealth Alliance, „každý pokles má svůj čas“ a trh si často nachází cestu k růstu, i přes krátkodobé otřesy. Dlouhodobý investor by proto neměl jednat unáhleně na základě jedné negativní zprávy. Trh zůstává citlivý na rétoriku, ale současné fundamenty stále vytvářejí prostor pro růst – zvláště pokud geopolitické napětí nepřeroste v otevřenou obchodní válku.
Can EUR/USD buyers clear the 1.1280 resistance, or will sellers regain the initiative and lock the pair back inside the 1.11 area? We will likely get answers over the coming week, even though the economic calendar isn't packed with major releases. Key publications include ZEW and PMI indices, which will shed light on current sentiment in the European economy and prospects for business activity. China's GDP data will indirectly affect EUR/USD by influencing overall risk appetite. The degree of risk-off sentiment will also depend on developments in the so-called "Iran case," given renewed attempts at diplomatic dialogue.
Thus, on one hand the week looks almost empty in terms of informational "content." On the other hand, even secondary releases can drive higher volatility in EUR/USD right now, as market participants interpret them in the context of the major macro reports already published.
On Tuesday, October 20, Germany will publish the ZEW indices. September's report showed a mixed picture: the German expectations index edged up from 34.2 to 34.7 points, and the current-situation assessment improved from -61.1 to -47.1. However, the euro-area expectations index fell from 31.4 to 25.8, even though the current-conditions assessment rose from -21.5 to -13.9. In plain language this means the overall situation improved in September, but confidence in a sustained recovery did not increase.
October forecasts point to a decline in the German expectations index: published consensus estimates lie in the 31-33 range. Similar dynamics are expected in the euro area. A weaker reading would weigh on the euro and deepen doubts about the resilience of the European recovery.
For the European Central Bank, this is a secondary but still relevant argument for a more cautious stance: expensive energy both fuels inflation and constrains growth, raising the specter of stagflation. In such conditions further rate hikes could further weaken an already fragile recovery, while waiting risks prolonging the fight against price pressures. Based on recent ECB speeches, the central bank is leaning toward caution to avoid undermining growth. Therefore weak ZEW readings could strengthen expectations of a pause in rate increases and put downside pressure on the euro.
On Friday, October 23, more important macroeconomic data for the euro will be published — the preliminary October PMI indices — which will help assess business-activity conditions in the eurozone's manufacturing and services sectors. Unlike the ZEW surveys, which focus primarily on expert expectations, PMIs are compiled from company surveys and reflect month-on-month changes in activity.
Last month, Germany's composite PMI rose from 51.8 to 53.8, and the services PMI rose from 49.7 to 52.9 (i.e., back into expansion). The manufacturing index, by contrast, edged down from 54.3 to 53.9. October forecasts call for the composite PMI to fall to 53.0, while the services index is expected to tick up slightly to 53.1. The manufacturing PMI is also forecast to tick up a little — from 53.9 to 54.0. In other words, growth is expected to persist but without repeating September's strong jump in overall activity.
In the eurozone, the composite PMI rose in September from 52.0 to 53.1, manufacturing from 52.7 to 52.9 and services from 51.6 to 53.0. October forecasts imply a decline in the composite PMI to 52.3. The manufacturing index is expected to slip slightly from 52.9 to 52.8, and the services measure from 53.0 to 52.8.
That dynamic would signal a slowdown in business activity, although the indices would remain above the 50-point expansion threshold. For the ECB, not only the headline PMI readings matter but also the report's price components. If the economy remains resilient and firms keep raising selling prices, proponents of further rate hikes would gain ground. But if new orders fall amid rising costs, the central bank faces a tougher choice: tighten to curb inflation and risk further slowing the economy, or pause despite price pressures. In short, weakening orders alongside rising input costs would sharpen the stagflation dilemma.
US PMIs will be released the same day. In September, the US composite PMI rose from 56.0 to 58.4, the services PMI from 56.5 to 58.8 and the manufacturing index was 55.9 — all comfortably in expansion. This month the composite PMI is expected to ease to 57.6, services to 57.9 and manufacturing to 55.6. Despite the expected "nominal" slowdown, all three indices would remain well above 50, reflecting reasonably solid activity. If price components also remain high, the dollar could get extra support: the combination of a resilient economy and persistent inflationary pressure would make it more likely the Federal Reserve maintains a tight policy stance.
On Monday, China will publish Q3 GDP growth data. Most analysts expect the Chinese economy to accelerate from 4.3% to 4.4% year-on-year and from 0.9% to 1.1% quarter-on-quarter. That would mean a moderate pick-up in activity.
A "green" (better-than-expected) print could reduce fears of a global slowdown and lift risk appetite. In that case, safe-haven demand for the dollar would likely ease, giving EUR/USD additional support. If the release disappoints, market participants will have another reason to doubt the durability of China's recovery and, by extension, global demand. An increase in risk-off sentiment would favor the greenback and weigh on the pair.
Secondary US releases will help complete the picture of the US economy. Housing data and unemployment claims will be in focus. After strong inflation prints and weak Nonfarm Payrolls, traders need to assess how resilient the US economy is to high interest rates and whether the Fed has room for further tightening.
US housing data are due Tuesday. Consensus expects housing starts to rise from an annualized 1.275 million to 1.30 million, while building permits may edge down slightly from 1.403 million to 1.385 million. Existing-home sales are expected to rise 0.5% month-on-month after a prior 0.3% rise. This combination points more to stabilization in the US housing market than a vigorous recovery — activity is gradually picking up, but permit trends do not suggest a material acceleration in construction soon.
On Thursday, market attention will turn to US initial jobless claims. Initial claims are forecast to tick up slightly from 199k to 200k, and continuing claims from 1.710m to 1.712m. If the prints match forecasts, they will not indicate a material deterioration. Low initial claims mainly signal the absence of mass layoffs but do not by themselves prove robust job creation, so such results would not negate the weakness seen in the Nonfarm Payrolls report. A large rise in either series would worry dollar bulls more: it would signal not only more job losses but also difficulty finding new employment.
From a technical perspective, EUR/USD still has short-term potential to continue the correction, although the reversal of the downtrend is not yet confirmed. On the H4 timeframe, price trades above the middle Bollinger Band and above Tenkan-sen and Kijun-sen, but remains inside the Kumo cloud. Key resistance remains at 1.1280, where the upper Bollinger Band coincides with the upper Kumo boundary on H4 (and on D1, this level corresponds to the middle Bollinger Band).
On the daily chart, the picture remains bearish: the Bollinger Bands slope downward, price sits between the middle and lower band, and it is below Kijun-sen and the Kumo. However, being above Tenkan-sen reflects strengthening buyer pressure, though it remains within a correction so far.
If buyers clear 1.1280 and close above it, they will open the way to the next significant barrier at 1.1370 (the daily Kijun-sen). But if buyers fail to take the 1.1270-1.1280 area and price falls below the H4 middle Bollinger Band target near 1.1200, that would signal weakening upside momentum. In that case, the pair could return to the 1.11 area, with the prospect of further declines to 1.1140 (the H4 lower Bollinger Band) and then to the recently updated yearly low near 1.1114.
SZYBKIE LINKI
ForexMart is authorized and regulated in various jurisdictions.
(Reg No.23071, IBC 2015) with a registered office at First Floor, SVG Teachers Co-operative Credit Union Limited Uptown Building, Corner of James and Middle Street, Kingstown, Saint Vincent and the Grenadines
Restricted Regions: the United States of America, North Korea, Sudan, Syria and some other regions.


 Skontaktuj się z ForexMart